

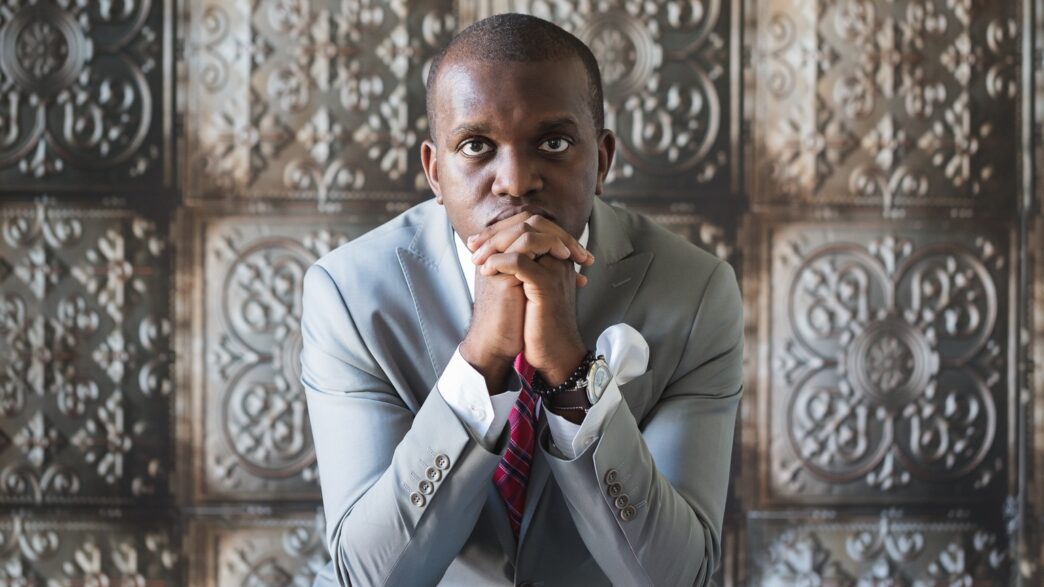
Seun Mafa is a United States-based consultant working across leadership, AI governance and workforce development. His experience includes supporting U.S. government projects and working across Africa, Europe, Australia and Asia. He is the founder of Ignite Consults and 5Africa. An author of three books, Mafa tells Economy Post why many professionals reach their 40s with limited investments despite decades of earning. He also examines how artificial intelligence is reshaping career prospects and why professionals over 40 must combine their experience with new skills to remain economically relevant.
In your book, ‘The Drug Called Salary,’ you describe salary as something people can become dependent on. At what point does a dependable salary become a financial trap, and why do many professionals struggle to recognise this?
A salary becomes a trap when losing it would collapse the whole structure of your life, and fear of that possibility begins to make your decisions for you. You may earn well, but every increase is already committed to a larger house, more debt or new obligations. There is little room to save, learn or change direction.
That dependence can be hard to recognise because it often looks like success from the outside. The title improves, the car improves, and people congratulate you. But your freedom has not improved. The question I want readers to ask is: what is this salary helping me build beyond the next payday? Paid employment can be a strong foundation. The problem starts when we stop using it to create options.
Many people spend decades building careers, earning salaries and supporting extended families but have little wealth to show for it. What are they getting wrong about money, financial planning and wealth creation?
I would not assume everyone with limited wealth has been careless. Some people have carried extraordinary responsibilities on incomes that never matched the demands placed on them. Supporting family is real work, and inflation can make progress difficult to see.
Where there is room to act, a common mistake is treating income as wealth. Income is what comes in; wealth includes what you retain and build after obligations. A higher salary can disappear just as quickly as a smaller one if spending rises alongside it. People need a clear picture of their debts, regular expenses, savings and assets. Put a plan behind each pay rise. Decide what will improve life today and what will strengthen the future, rather than allowing the entire increase to become another monthly commitment.
READ ALSO: Dangote’s wealth jumps $19.9bn to $51.3bn after refinery begins IPO
For someone earning a good salary but depending entirely on it to meet monthly obligations, how can they begin building alternative income streams without jeopardising their existing job or family responsibilities?
Start with one small, testable opportunity that builds on something you already know. That could be a specific consulting service, training, a useful product or another activity for which there is an identifiable customer. Find out whether someone will pay before spending heavily on branding, equipment or stock.
Protect the job that pays the bills while testing the idea. Use your own time and resources, understand your employment terms, and set a limit on the money and hours you can afford to commit. Track actual profit after expenses and taxes, not just sales. A side business that consumes every evening and loses money is not creating independence. Build evidence of demand, repeat customers and a workable routine before expanding. You do not need five income streams immediately; you need one additional source that works.
Turning 40 often brings new financial and personal realities, including ageing parents, children’s education, mortgages and retirement concerns. What financial decisions should people be making before reaching this stage of life?
Before forty, people should begin planning for responsibilities that are predictable even when their exact timing is uncertain. School fees, housing, support for parents and retirement should each have a place in the budget. An emergency fund should be kept accessible, separate from money intended for long-term investment.
Review expensive debt, understand your pension arrangements and contribute consistently toward retirement. Consider what would happen to dependants if the main income stopped, and review the protection available through work and personally. Couples and relatives also need honest conversations about who can provide what. Avoid making housing or education commitments that only work if income rises every year. Forty should be a review point, not the first time someone asks how the household will function without a salary.
Many African professionals face pressure to maintain lifestyles, support relatives and meet societal expectations. How does this culture affect their ability to accumulate wealth, invest and achieve financial independence?
In many African families, one person’s income supports several households. That solidarity can pay for education, keep relatives housed and create opportunities that would otherwise not exist. The difficulty comes when support has no limits and the provider’s own future is treated as optional.
READ ALSO: Industries that created world’s 30 wealthiest people
People can end up financing an appearance of success while quietly borrowing to meet expectations. I would encourage a defined family-support budget and honest conversations about what is sustainable. Where possible, support should also help people develop earning capacity rather than create an indefinite obligation. You can care about your family and still protect your retirement, your children’s needs and your emergency savings. Sustainable generosity requires the person giving to remain financially stable.
For someone who wants to leave paid employment after 40 and start a business or pursue a different career, what financial preparation should happen before making that transition? How much financial cushioning is realistic?
Separate the household transition budget from the business budget. Work out the essential monthly cost of keeping the family secure, including debt payments, health costs, school fees and support commitments. Then calculate the business’s startup costs and the time it may take to generate dependable cash.
For someone giving up a steady salary, I would use six to 12 months of essential household expenses as a planning range to test, not as a universal answer. A sole earner with dependants or an untested business may need more. Someone moving into another confirmed role faces a different situation. The practical test is whether the plan still works if revenue arrives later than expected. Validate demand, reduce avoidable fixed costs and agree on a point at which you will reassess. A staged transition is often more manageable than making resignation the first step.
You have worked across Africa, Europe, Australia and Asia. What differences have you observed in how professionals approach salaries, personal wealth, career mobility and retirement, and what lessons can African workers learn?
The lesson I would draw from working across different settings is that financial behaviour cannot be separated from the environment around it. Pension arrangements, access to credit, healthcare costs, family obligations and the availability of another job all affect how much risk someone can take. There is also enormous variation within each country, so I would avoid ranking entire continents as financially disciplined or undisciplined.
READ ALSO: Abdulsamad Rabiu’s wealth soars 86% as Nigerian billionaires overtake South African peers
For African professionals, the useful lesson is to build a plan around the systems and obligations they actually face. Know what your pension is likely to provide, keep your skills portable, maintain professional relationships outside your employer and build assets alongside income where you can. Copying another person’s lifestyle tells you very little about the financial protections behind it. Learn from useful practices elsewhere, but make the numbers work in your own circumstances.
With artificial intelligence reshaping workplaces and threatening or changing traditional jobs, how should professionals over 40 reposition themselves to remain economically relevant and protect their earning capacity?
Start by examining the tasks inside your job. Which are repetitive? Which require judgment, trust, negotiation or responsibility for an outcome? Then learn how AI can assist with the work while strengthening the expertise needed to judge its output.
A professional over 40 often has valuable context: knowledge of customers, systems, regulations and the consequences of getting things wrong. Combine that experience with practical AI skills. Choose one useful workflow, such as preparing a first draft, analysing nonconfidential information or organising a report, and learn how to check accuracy and improve the result. Understand your organisation’s rules for data use. Build examples of improvements you can explain and demonstrate. The goal is to become more effective at solving problems, not simply to collect certificates or learn fashionable terminology.
Many people equate career success with promotions, bigger salaries, job titles and professional recognition. How can individuals distinguish genuine personal progress from the pursuit of societal validation, particularly when their financial security remains fragile?
Ask what has actually improved beneath the recognition. Are your debts becoming more manageable? Do you have greater savings, stronger skills, healthier relationships and more control over your time? Can you make a reasonable choice without being paralysed by the loss of a title or other people’s approval?
A promotion can represent genuine progress, but it should be assessed alongside its costs. More income that comes with unsustainable obligations may leave you more exposed. I would also ask: if nobody could see this achievement, would I still want it? That question helps separate a goal you value from a performance you are maintaining for others. Define success in terms you can live with, then measure your career against that definition.
If you were advising a 45-year-old African professional who has a steady job, significant family responsibilities, limited investments and no clear retirement plan, what practical five-year financial and career strategy would you recommend?
I would start with a clear household picture and build the plan in stages.
Year one: list income, essential spending, debts, savings, pension balances and family commitments. Build an initial cash buffer, make a plan to reduce high-interest debt and establish a sustainable monthly amount for retirement saving. Agree on limits for discretionary spending and family support.
Year two: strengthen earning capacity. Choose a skill that employers or customers will pay for, apply it in real work and document the results. Review compensation and explore better-paid roles without abandoning current income prematurely.
Year three: test one additional source of income with a controlled budget. Continue building reserves and making regular retirement contributions. Match investments to the time the money will be needed, and avoid concentrating the entire future in one venture or asset.
Year four: review progress against actual numbers. Increase contributions where income allows, reduce remaining expensive obligations and expand only the activities that show dependable demand and profit.
Year five: reassess the retirement timeline, family needs and career options. Decide whether staying employed, changing roles or moving toward a business now offers the strongest position. The goal is a household with more resilience and choices, not a promise that everyone can retire in five years.